Maximize Real Estate Tax Write-Offs
Trusted by 500+ real estate investors
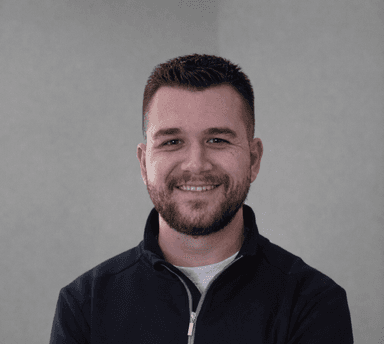
Who You're Working With
Stan Kocev
Cost Segregation Representative.
Free Instant Estimate
Cost Segregation Calculator
27.5-yr depreciation · 20–27% reclassified
Common rates: 24%, 32%, 37%, 39.6%
Estimated First-Year Tax Savings
$61,673 – $83,258
At 32% tax rate · Apartment / Multifamily (27.5-yr schedule)
Reclassified to 5 & 15-yr Property
$200,000 – $270,000
20%–27% of purchase price · deducted in Year 1 vs. over 27.5 yrs
*Incremental savings vs. standard 27.5-yr straight-line depreciation. Assumes ~20% land value. Does not constitute tax advice.
Want to lock in these exact savings on your next tax filing?
Stan Kocev will personally deliver your official CSSI preliminary study within 48 hours — free, no obligation.
How It Works
The Tax Strategy Top Real Estate Investors Use
Cost segregation isn't a loophole — it's an IRS-recognized engineering study that changes which depreciation schedule your building components fall under.
Engineering Study
A CSSI-certified engineer inspects or reviews plans for your property and identifies every component — roofing, wiring, landscaping, flooring — and assigns each to its correct MACRS class life.
Reclassification
Instead of depreciating the entire building over 27.5 or 39 years, 20–35% of the cost is moved to 5 and 15-year property, eligible for 60–100% first-year bonus depreciation under current law.
Accelerated Deductions
You claim the accelerated depreciation on your tax return. For a $2M property at a 37% rate, this typically means $150k–$270k in tax savings in Year 1 alone — without selling or refinancing.
What Is Bonus Depreciation?
The Tax Cuts and Jobs Act of 2017 introduced 100% first-year bonus depreciation for qualifying 5, 7, and 15-year MACRS property. This allowed investors to immediately deduct the full value of reclassified components in Year 1. The rate has since phased down — it was 80% in 2023, 60% in 2024, and 40% in 2025 — but pairing cost segregation with any remaining bonus depreciation still produces outsized front-loaded deductions compared to straight-line schedules.
The STR (Short-Term Rental) Loophole
Short-term rentals rented for fewer than 7 days average stay are not classified as "rental real estate" under IRC §469. This means losses from a cost segregation study on an STR property can offset active ordinary income — including W-2 wages and business income — without the $25,000 passive-loss cap or the real-estate professional designation required for long-term rentals. For high-income earners in the 37%+ bracket who own even a single Airbnb-style property, this is one of the most powerful tax strategies available.
MACRS 5-Year and 15-Year Acceleration Explained
Under the Modified Accelerated Cost Recovery System (MACRS), personal property like appliances, carpeting, and certain fixtures depreciate over 5 or 7 years using a 200% declining-balance method. Land improvements such as parking lots, landscaping, and sidewalks qualify for a 15-year, 150% declining-balance schedule. Both classes accelerate deductions dramatically compared to the 27.5-year residential or 39-year commercial straight-line default. A cost segregation study is the IRS-required documentation to substantiate these reclassifications in an audit.
For CPA & Tax Professional Partners
Work directly with Stan Kocev as your dedicated CSSI liaison. Preliminary studies are provided at no cost and you are charged only upon completion of a full engineering report. Every study includes detailed asset schedules, IRS audit support documentation, and a cost basis reconciliation your clients can hand directly to their tax preparer. CSSI maintains E&O insurance and stands behind every report in the event of an IRS challenge.
$2.4B+
Depreciation Identified
65,000+
Studies Completed Nationwide
48 hrs or less
Preliminary Estimate Turnaround
100%
IRS Audit Success Rate
FAQ
Common Questions
Ready to See Your Exact Numbers?
Use the calculator for a free instant estimate, then click “Get Official Preliminary Study” and Stan will personally deliver your CSSI-backed report within 48 hours.
Try the Calculator